TL;DR
At 22, you may have student debt, a small bank balance and very little invested. That does not mean you are behind. Net worth gives you an honest starting point by showing what you own minus what you owe. Tracking it early helps you reduce harmful debt, start investing sooner and build habits that can matter for decades.
What Is Net Worth and Why Should You Care at 22?
The Number That Matters More Than Your Salary
At 22, financial advice often focuses on three numbers: your starting salary, your credit score and the amount in your bank account.
Each matters. Your salary affects how much you can save. Your credit history may affect future borrowing. Your cash balance helps you handle bills and emergencies.
But none of those numbers shows your full financial position.
Someone earning $65,000 with $32,000 in student loans, $4,000 in credit card debt and no investments may be in a weaker position than someone earning $48,000 with modest savings, no expensive debt and regular retirement contributions.
Net worth combines the full picture. It shows the assets you have built and the debts still reducing your progress. That is why learning to track it at 22 can be more useful than comparing your first paycheck with someone else’s.
Net Worth in Plain English
Net worth is simple:
Net Worth = Everything You Own − Everything You Owe
What you own may include checking and savings accounts, retirement accounts, investments, cash and a vehicle at realistic resale value.
What you owe may include student loans, credit card balances, auto loans, personal loans or money borrowed from family.
Suppose you have:
| Financial Item | Amount |
| Savings and checking | $2,500 |
| Workplace retirement account | $1,000 |
| Car resale value | $11,500 |
| Total assets | $15,000 |
| Student loans | -$20,000 |
| Net worth | -$5,000 |
A negative $5,000 net worth does not mean you have failed. It means you currently owe more than you own. For a recent graduate or someone starting adult life with education debt, that may simply be the beginning of the story.
The important question is what happens next. Does the student loan balance begin to fall? Do you avoid new credit card debt? Does your retirement balance begin to grow? Net worth turns those decisions into something measurable.
Why Starting at 22 Can Be Worth More Than $500,000
Early adulthood has one financial advantage that becomes impossible to recover later: time.
Assume two people each invest $300 per month and earn a hypothetical 7% annual return, compounded monthly. Actual investment returns are not guaranteed, and markets can decline. This example simply shows what time can do under the same assumption.
The first person starts at age 22 and invests until age 65, a total of 43 years. They contribute $154,800 of their own money. Their projected balance at 65 is approximately $982,839.
The second person waits until age 32 and invests the same $300 per month until age 65, a total of 33 years. They contribute $118,800. Their projected balance is approximately $463,219.
| Starting Age | Monthly Investment | Value at 65 at Hypothetical 7% |
| 22 | $300 | $982,839 |
| 32 | $300 | $463,219 |
| Difference | $519,620 |
The earlier investor contributed only $36,000 more, yet finishes with more than half a million dollars of additional projected value. The difference comes from giving early contributions ten more years to potentially grow.
This does not mean you must invest $300 immediately. Starting with $25 or $50 per month can still build the habit. The key lesson is that waiting until money feels perfect can be far more expensive than beginning small.
What a Normal Financial Starting Point Looks Like
According to the Federal Reserve’s 2022 Survey of Consumer Finances, the median family net worth for households with a reference person under age 35 was $39,000.
That figure is useful context, but it is not a fair scorecard for every 22-year-old. The under-35 group includes people in their early 30s who may have had years to build retirement savings, reduce debt or purchase a home.
At 22, it is common to be early in the process: perhaps you are finishing education, beginning a first full-time job, renting your first home or starting to repay loans. A negative or low starting net worth does not define where you will be at 32.
Direction matters more than comparison. Moving from negative $12,000 to negative $7,000 is progress. Reaching zero is a milestone. Building your first $10,000 of positive net worth proves that the system is working.
Your First Three Financial Moves
1. Use Any Available Employer Retirement Match
When your first full-time job offers a retirement plan with an employer match, learn the rules. Contributing enough to receive an available match can add employer money to your retirement savings, subject to vesting and plan terms.
2. Open a Roth IRA When Eligible
A Roth IRA may be useful for a young worker with taxable compensation, subject to IRS income and eligibility rules. For 2026, the annual IRA contribution limit for someone under age 50 is $7,500, or taxable compensation for the year when that amount is lower.
You do not need to contribute the maximum to begin. Fifty dollars per month is $600 invested across a year and, more importantly, a system you can increase as income grows.
3. Stop High-Interest Debt Before It Grows
Credit card debt can make net worth difficult to build because interest charges take money away from future saving. Use credit carefully, pay balances on time and avoid carrying expensive debt for ordinary lifestyle spending.
Student loans may require a longer plan. Know your balance, rate and required payment, then keep it visible in your net worth calculation.
Start Tracking Your Net Worth Today
Your first net worth number may not impress you. That is not the point. It gives you a baseline you can improve.
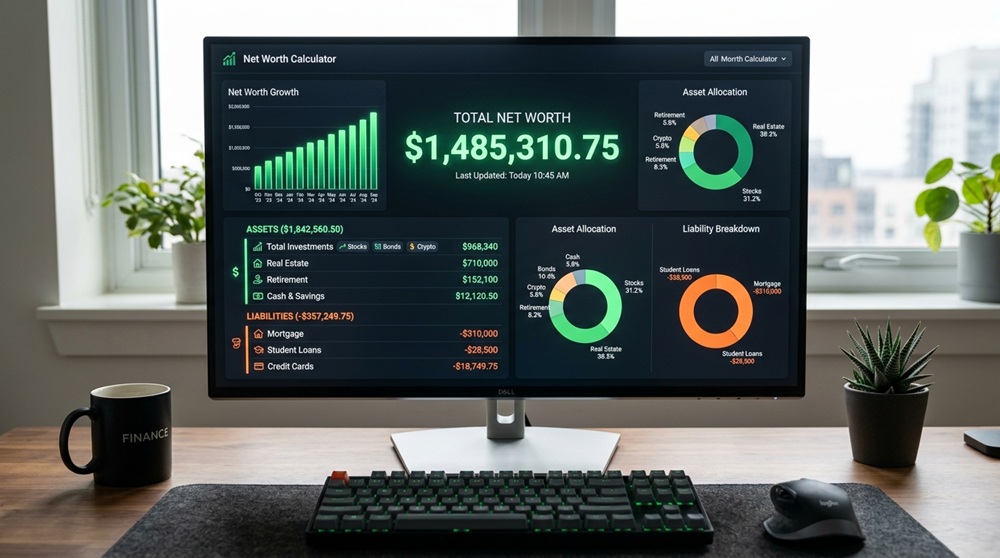
To start tracking your net worth, enter what you currently own and what you owe. The free tool requires no signup, gives an instant result and lets you compare future updates against your starting point.
Check the number every three months. Watch debts decline and new assets appear. For more straightforward personal finance resources, visit NetlyWorth.
You Are Early Enough to Make Time Work for You
At 22, you do not need a high net worth to be on the right path. You need an honest starting number, a plan for debt and the willingness to begin building assets before life becomes more expensive.
Your salary may change. Your living costs may change. Your goals almost certainly will. A habit of tracking net worth helps you see whether your decisions are taking you forward. Start now, even with a small number. Time can do far more with a modest beginning than most people realize.